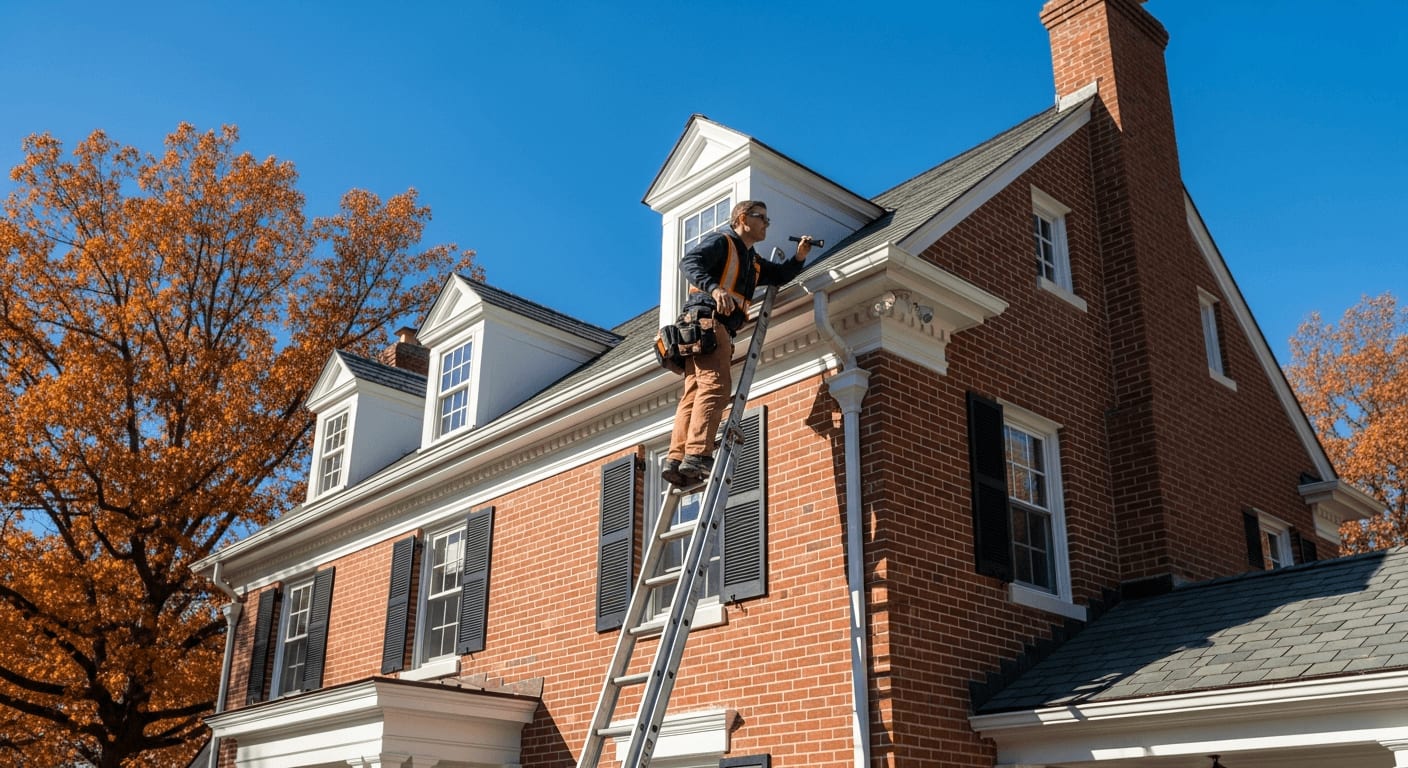
Before making an offer, discuss what you need to learn about the property, who can investigate it, and which contract provisions would permit that work. Inspection findings are information for a decision. They do not automatically create a right to a repair, credit, extension, or cancellation.
Define the scope before choosing the provider
Ask the inspector for the written inspection scope, exclusions, access requirements, reporting method, and relevant qualifications. Identify questions that may need a separate specialist, such as a sewer line, chimney, unusual roof, structure, moisture source, or environmental concern. Avoid assuming a construction year alone determines the required scope.
The CFPB's home-inspection guidance distinguishes an independent inspection from the lender's appraisal. Ask your lender separately about property-condition requirements and any loan-specific testing or treatment requirements. A general claim that a test is required for “most loans” is not a substitute for that answer.
Turn findings into a decision record
| Record field | What to capture |
|---|---|
| Observation | Exact location, report reference, photographs, and access limitations |
| Significance | What the inspector or specialist says, including uncertainty |
| Follow-up | Additional access, testing, diagnosis, permit research, or specialist review |
| Cost and timing | Written scope and estimate where available, not a guessed allowance |
| Contract decision | Applicable notice or response deadline and the options your advisers identify |
Separate safety concerns, major-system questions, and maintenance or cosmetic items for discussion. The categories help organize the work; they do not determine what the seller must do.
Compare repair, credit, and other responses
A repair proposal needs a scope, qualified provider, completion date, documentation, and a way to verify the work. A credit proposal needs lender and settlement review; do not assume it becomes unrestricted cash to the buyer. A price adjustment may have different cash-flow implications. Some issues may call for more investigation before any proposal is useful.
Have your agent and, where needed, attorney explain what the contract permits and how to preserve any available rights. Do not assume either party can simply walk away after a particular finding.
Close the information loop
Save reports, estimates, written responses, completion documents, and unresolved questions in one file. Verify agreed work using the appropriate specialist and the transaction's procedures. For sellers organizing a response, see the inspection and repair-request record.
Bring the property address, proposed contract, timing, and your known concerns to a conversation with Liz. The useful plan is specific to the property and agreement, not a universal credit formula.